
Richard Evans
I cover specialty gases and semiconductor chemicals used throughout wafer fabrication. My research focuses on the materials required for deposition, etching, cleaning, lithography, and other critical manufacturing processes. I write for this website because semiconductor production depends on a complex chemical supply chain that is often overlooked when discussing chip manufacturing. Even small changes in material purity, availability, or manufacturing capacity can affect production continuity and process performance. My research follows specialty gas demand, electronic chemicals, supply capacity, manufacturing localization, logistics, and the changing material requirements of advanced semiconductor processes. I pay particular attention to materials used in advanced logic, memory, and high-volume manufacturing. I also examine supply-chain resilience and regional manufacturing strategies. As semiconductor production becomes more geographically diversified, chemical and gas suppliers must adapt their production and distribution networks. My goal is to help readers understand the materials infrastructure behind semiconductor manufacturing and the market forces influencing specialty chemical and gas suppliers.
Semiconductor materials analyst covering specialty gases, electronic chemicals, deposition, etching, cleaning, supply chains, and manufacturing localization.
Richard Evans is a semiconductor materials analyst focused on specialty gases and electronic chemicals used throughout wafer fabrication. His research covers materials used in deposition, etching, cleaning, lithography, and other critical manufacturing processes.
Richard examines specialty gas demand, electronic chemical consumption, material purity, production capacity, logistics, and supplier development. His coverage spans advanced logic, memory, and high-volume semiconductor manufacturing.
Supply-chain resilience is a major theme in his research. Semiconductor manufacturing is becoming more geographically distributed, creating new requirements for local material production, storage, transportation, and supply security.
Richard also follows the increasing material requirements associated with advanced process technologies. Through his articles, he explains how semiconductor manufacturing trends translate into demand for specialty gases and chemicals and how suppliers are adapting to changes in the global chip industry.
His Articles
2026 Investor Structure Shifts in Memory Thematic ETFs – Retail Out, Institutions In
In early 2026, AI memory suddenly became the center of the hardware universe. High-bandwidth memory, DRAM, NAND, and storage systems turned into the choke point for training and running large models, and the first wave of memory-focused ETFs arrived just in time to catch that realization. The result was explosive: assets piled in, performance numbers looked surreal, and social media declared “the memory trade” as the new frontier. But as the months passed, a quieter story unfolded underneath the price charts—who actually owns these memory ETFs is changing.
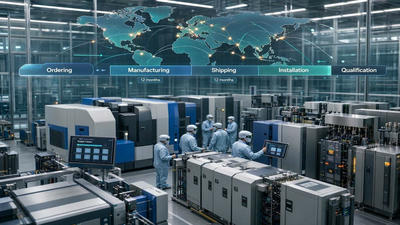
Semi Equipment Procurement Lead Times Extended to 12 Months
In semiconductor manufacturing, time is as critical a resource as capital. When lead times for key tools stretch from a few months to a full year, the ripple effects can reshape fab build schedules, technology roadmaps, and industry supply dynamics. The extension of equipment procurement lead times toward the 12‑month mark is more than an operational inconvenience;
Drawdown Magnitude and Recovery Duration of Semis During USD Liquidity Crises
Semiconductor stocks have a habit of reminding investors that progress is not a straight line. Periods of explosive growth, fueled by new technologies and insatiable demand for chips, are often followed by brutal drawdowns when the macro environment turns. Among the most stressful of these episodes are USD liquidity crises—moments when dollar funding dries up, credit spreads widen, and global markets scramble for access to the world’s reserve currency. In those periods, the magnitude of semiconductor drawdowns and the duration of their recoveries tend to reflect not just sector-specific forces, but the broader macro linkage of interest rates, exchange rates, credit conditions, and commodities.
2027 HBM Market Size Forecasts: The Upper/Lower Bound Divergence Among Major Institutions
High Bandwidth Memory (HBM) has transitioned from a niche technology to a central pillar of the AI and high‑performance computing ecosystem, and by 2027 it is expected to sit at the heart of GPU, accelerator, and advanced CPU platforms worldwide. Against that backdrop, financial institutions and industry research houses have been racing to forecast the market size for HBM, yet their estimates vary widely. Some project an aggressive, multi‑fold expansion with tight supply and premium pricing, while others caution that bottlenecks and substitution effects could cap growth.
QoQ Revenue Growth Ranking of Global Top 10 Semiconductor Firms
Quarter‑on‑quarter (QoQ) revenue growth for the world’s largest semiconductor firms offers a fast, quantitative snapshot of who is winning incremental demand at any given point in the cycle. It does not tell the whole story of structural strength, but it shows where momentum is moving in the near term—whether toward AI accelerators and advanced nodes, toward memory and storage, or toward analog and power devices tied to autos and industrial markets.