
James Wilson
My research focuses on semiconductor cycle transitions, especially the periods when inventories, utilization, pricing, demand, and capital expenditure begin moving from one phase to another. I am particularly interested in the signals that appear before a major industry trend becomes obvious in company financial results. I write for this website because semiconductor cycle turning points are often difficult to identify when individual indicators are considered separately. Inventory may improve while pricing remains weak, utilization may recover before capital expenditure increases, or demand may strengthen in one segment while another remains under pressure. My work is focused on bringing these signals together into a coherent framework. I monitor semiconductor inventories, wafer starts, utilization rates, pricing trends, equipment spending, capital expenditure plans, and demand indicators across major semiconductor segments. I also compare these developments with historical industry patterns to understand how current conditions differ from previous cycles. Another part of my work involves semiconductor market valuations and investment themes. Financial markets frequently react to expectations about future industry conditions rather than current operating data alone. I therefore follow the relationship between cycle indicators, earnings expectations, sector valuations, and investor sentiment. On this website, I aim to provide readers with a disciplined way to think about semiconductor cycle transitions. My objective is not to claim that every market movement can be predicted, but to identify the fundamental signals that can help explain why the semiconductor industry is moving from one stage of the cycle to another.
Semiconductor cycle analyst specializing in turning points, inventory, utilization, pricing, demand, and capital expenditure. James focuses on identifying the fundamental signals behind changes in industry conditions.
James Wilson is a semiconductor cycle analyst who specializes in identifying changes in the underlying conditions of the global semiconductor market. His work focuses particularly on the periods when an industry moves from contraction to recovery, from expansion to normalization, or from strong demand toward a new phase of adjustment.
James monitors a broad range of semiconductor indicators, including inventories, wafer starts, fab utilization, pricing, capital expenditure, equipment spending, and end-market demand. Rather than relying on a single indicator, he studies how several signals develop together over time.
His research also examines differences between semiconductor segments. Memory, logic, foundry, automotive, consumer electronics, AI infrastructure, and other markets can move through their cycles at different speeds, making sector-level analysis important when evaluating the broader industry.
James follows semiconductor valuations and investment themes as another component of his research. His work examines how changing expectations for industry fundamentals can influence earnings expectations and the valuation of semiconductor companies and sector indices.
Through his articles, James provides readers with a structured framework for understanding semiconductor cycle transitions and the measurable industry indicators that can help explain changing market conditions.
His Articles
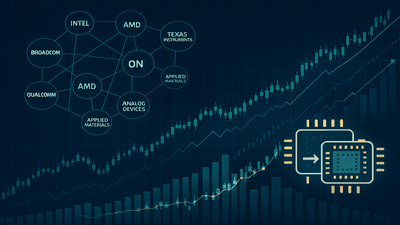
Global Semi M&A Value Hits 5-Year High, Consolidation Wave Accelerates
When global semiconductor M&A value hits a five‑year high, it is more than a headline about deal flow—it is a structural signal. Rising transaction values and a thick pipeline of strategic deals tell us that industry leaders believe scale, integration, and portfolio breadth are increasingly essential in a market shaped by AI, automotive electrification, industrial automation, and geopolitical tension. The current consolidation wave is not the first the sector has seen, but it is distinct in scope and motivation.
SOXX vs. SMH: The Ultimate Comparison of Holdings Structure and Expense Ratios
When investors look at semiconductor ETFs, SOXX and SMH are usually the first two names that come up. They both offer straightforward exposure to the chip industry, both are widely traded, and both are used as core tools for expressing a view on semiconductors. But while they look similar on the surface, the way they are built is meaningfully different. Those differences show up most clearly in holdings structure and, to a lesser extent, in expense ratio.
Stock Selection Logic and Alpha Validation of ESG-Themed Semi ETFs
Semiconductor themed ETFs are no longer just about growth and cycles. A growing subset now layers environmental, social, and governance (ESG) criteria on top of traditional sector exposure. These ESG semi ETFs promise two things at once: access to one of the market’s most powerful secular themes, and alignment with sustainability and governance standards. The pitch is appealing, but it raises two hard questions. First, how exactly are these stocks being selected? Second, does the ESG overlay help, hurt, or leave alpha unchanged?